
There’s a popular idea about retirement money: when you need cash, skip the bank, borrow from your own retirement plan, and pay the interest back to yourself. I recently worked through whether it holds up, from which accounts can actually lend to what the loan does to your taxes. The first check is easy to miss, and it’s a single line on the account screen:
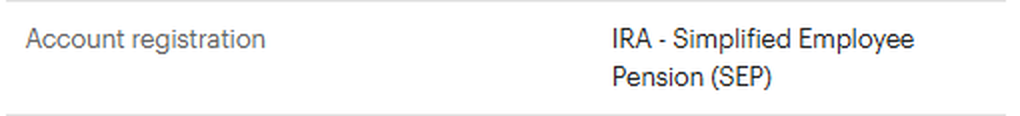
A Simplified Employee Pension IRA (SEP IRA) can’t make a loan. Neither can any other Individual Retirement Account (IRA). Product names and marketing pages blur that distinction; the registration line doesn’t.
The appeal is easy to see. You need cash for a down payment, a piece of equipment, or a slow quarter. A Solo 401k loan skips the lender and the credit check, and every dollar of interest lands back in your own account.
Paying yourself interest is not the same as earning a return.
Only some accounts can lend to you
IRAs, whether traditional, Roth, or SEP, don’t lend. Pledging one as collateral doesn’t work either, because the tax code treats the pledged amount as if you had taken it out. Loans come from employer plans, such as a 401(k), a 403(b), and some government 457(b) plans, and only when the plan’s own document allows them. Many low-cost plans for one-person businesses leave the loan feature out.
Before you move a dollar, read the account registration line, not the product name.
Employee or owner: you start from different places
Whether a plan loan is even on the table depends on which side of the paycheck you’re on.
If you’re a W-2 employee, your options are whatever your employer’s plan says. You don’t pick the plan or its terms. Many workplace 401(k) and 403(b) plans do offer loans, and repayment usually comes straight out of your paycheck, which makes it hard to miss a payment. The plan’s summary plan description (SPD), which your HR department or plan website can provide, tells you whether loans are allowed, how many you can have at once, and what happens to an unpaid balance if you leave the job. That last answer matters most, because leaving is the most common way a plan loan turns into a tax bill.
If you own the business, you choose the plan, which means you also choose whether it lends. A SEP IRA and a SIMPLE IRA, the two plans owners most often set up first, can’t make loans at all. A 401(k) can, if its document allows it. Two things are different for an owner. First, nobody runs your repayments through payroll unless you set that up; a missed payment is your problem to catch, and the plan’s grace period is short (generally no later than the end of the next calendar quarter). Second, if you have employees in the plan, a loan feature has to be available to all of them on a reasonably equivalent basis, not just to you. And if you are the only person in the plan, the plan’s future is tied to the business’s: when the business winds down, the plan often ends too, and an unpaid loan comes due.
An employee asks, “Does my plan allow this?” An owner asks, “Should my plan allow this?”, and then has to run it.
If you own the business: where I looked for a plan that lends
If you are the only employee of your business (spouses can join too), the plan you’re after is a one-participant 401(k), often sold as a “Solo 401(k).” What I found when I checked in late 2026 is below. Features change, so confirm each point with the provider before you rely on it.
The no-fee plans from large brokerages typically use the firm’s own standard document, and several of those leave out loans entirely. Fidelity’s Self-Employed 401(k) was one of them. I confirmed on a call that its document has no loan provision, and changing your own elections won’t add one.
E*TRADE (now part of Morgan Stanley) is the exception I found: an Individual 401(k) with no setup or annual fee, and published materials that say it permits loans. Those materials describe the standard five-year repayment term, and I could not find anything confirming the longer home-purchase term. If that term is your reason for borrowing, get the answer in writing before you open anything. And make sure the account you open is the 401(k). The SEP IRA is offered right alongside it, and the two are easy to confuse.
Then there are specialist plan-document providers, often called third-party administrators (TPAs). They charge a setup fee and a yearly fee, and loan features are much of what they sell. My Solo 401k Financial, for example, states in its published materials that a loan to buy your primary residence can run as long as your mortgage. Solo401k.com (Nabers Group) markets loans up to the legal maximum. Fees vary a lot between firms, and on a long loan the yearly fee matters more than the setup fee.
I have no referral, affiliate, or compensation arrangement with any provider named in this article.
A few things surprised me that the product pages don’t mention. You can often keep your current brokerage: some will hold a plan’s investments under another firm’s plan document (Fidelity calls this an investment-only, or non-prototype, account). The brokerage reviews the documents when you apply. It does not keep an approved list of providers, and it won’t recommend one.
If you already have a Solo 401(k), ask the new provider to restate it rather than open a new plan. A restatement keeps the same plan, with its original start date, on the new document. A new plan leaves you sponsoring two. Check that the form you sign is marked as a restatement.
The plan also needs an eligible sponsor, meaning a business with self-employment income. Ask about that first, especially after a loss year or a year with no owner pay. And a home-purchase loan doesn’t have to be secured by the home. Under the federal rules for plan loans, it can qualify for the longer term without a lien on the house, so there’s no second lien for your mortgage lender to deal with.
These are the questions I would ask every provider, in this order:
- Will you accept my business as the plan sponsor, given its current income?
- Can you restate my existing plan rather than start a new one?
- Does your document permit participant loans, including a home-purchase loan with a term longer than five years? What is the maximum term?
- Will the plan accept rollovers from the accounts I actually hold?
- What are the setup and yearly fees, and can my investments stay at my current brokerage?
“Loans permitted” is not the whole answer
A plan that permits loans still sets its own terms, within limits the tax code sets. You can generally borrow the lesser of half your vested balance or a fixed dollar cap in the statute. Repayment generally runs five years, with payments at least quarterly. A longer term is allowed for buying a principal residence, but only if the plan document includes it. Many don’t.
That last point decides whether a 401k loan for a down payment works at all. On the same balance, stretching repayment from five years to fifteen cuts the payment roughly in half. If the plan caps you at five years, the payment may be too large to qualify for the mortgage the loan was supposed to help with.
What borrowing does to your taxes
As long as the loan stays within the legal limits and you repay it on schedule, taking it out isn’t a taxable event. That’s the main advantage over a withdrawal, and it’s real. Most of the tax cost shows up elsewhere.
The interest is paid twice over, in a sense. Repayments come out of your take-home pay, after income tax. In a traditional (pre-tax) account, that money will be taxed again when you withdraw it in retirement. The principal isn’t taxed twice, because you weren’t taxed when you borrowed it, but the interest is. In a Roth 401(k), qualified withdrawals are tax-free, so this effect largely disappears. On a modest loan it’s a modest effect either way, but it undercuts the idea that the interest is free money moving from one pocket to another.
The interest isn’t deductible, even on a home purchase. Mortgage interest can be deductible because the loan is secured by the house. A plan loan used for a down payment is secured by your retirement account, not the house, so its interest generally gets no deduction. If you’re comparing a plan loan’s rate with a mortgage rate, compare them after tax.
A missed payment turns the loan into income. If payments stop and the grace period passes, the unpaid balance becomes a “deemed distribution.” It’s reported to you on a Form 1099-R and taxed as ordinary income, federal and usually state. If you’re under 59½, an additional 10% tax typically applies on top. That happens even though you never received any new cash.
Leaving the job, or the plan ending, can do the same thing. Many plans call the unpaid balance due when you separate from the employer; if it isn’t repaid, the plan “offsets” it against your account, and the offset is treated as a distribution. There is one relief valve worth knowing about: when a loan is offset because you left the job or the plan ended, you generally have until your tax-return due date for that year, including extensions, to put the same amount into an IRA or another plan and avoid the tax. That takes cash you may not have, which is exactly the situation that caused the offset.
Compare it with a withdrawal, not just with a bank. A straight withdrawal from a pre-tax plan is taxed as income right away, usually with the 10% additional tax if you’re under 59½, and the money can never go back in. Next to that, a loan you repay on schedule is the gentler option. Next to leaving the money invested, it isn’t.
These are the general federal rules as I understand them. Exceptions, state tax, and your own plan document can change the result, so check with a tax advisor before you act on them.
The real cost is the compounding you interrupt
This is the part the pitch skips, and it’s the one that matters most.
While the money is on loan, it isn’t invested. Your return on those dollars becomes the loan’s interest rate and nothing more. If the investments you sold would have grown faster than that rate, you lost the difference, and the loss compounds: the growth you missed in year one isn’t there to grow in years two through thirty.
When you borrow from a retirement account, you are in effect betting that the market will do worse than your loan rate over the life of the loan. Over short, bad stretches that bet can win. Over the long stretches retirement money is meant for, it typically hasn’t.
The best thing retirement money can do is stay invested and compound, untouched.
The strings you notice later
An outstanding loan generally can’t be rolled to another plan, so the flexibility to “move it later if we need to” is gone the day you borrow. And mortgage underwriters treat plan loans differently from one lender to the next. Ask yours how the payment will be counted before you borrow, not after.
When you owe back taxes
This is the one case where the math can flip, and it comes up most with owners who fell behind on estimated taxes in a lean year.
An unpaid IRS balance is expensive in a way the market isn’t: it’s certain. A late-payment penalty accrues every month the balance is open (it’s halved while you’re on an installment agreement, if you filed the return on time), and interest on both the tax and the penalty resets every quarter and compounds daily. Against a cost you know you’ll pay, a plan loan you repay on schedule can come out ahead, because it stops those charges and the loan itself isn’t taxable.
What doesn’t work is the move many people reach for first: withdrawing from the retirement account to pay the IRS. A voluntary withdrawal from a pre-tax plan is taxable income in the year you take it, usually with the 10% additional tax if you’re under 59½. You’d be creating a new tax bill to pay an old one, and you’d need to withdraw well more than you owe to net enough after tax. Oddly, if the IRS itself levies the account, the 10% additional tax doesn’t apply to the levied amount, but a withdrawal you choose to make to head off a levy gets no such relief. The IRS’s own procedures treat levying retirement accounts as a last resort, so waiting for one isn’t a plan.
Three alternatives deserve a look before you borrow. An installment agreement is usually available without much paperwork for smaller balances, and it cuts the penalty rate. If the balance comes from a first-time slip with a clean history, penalty relief may take a real bite out of it. And if the debt is larger than you can realistically repay, the IRS has settlement and hardship programs worth an hour with a tax professional before anything else.
Borrowing to pay the IRS only works if the loan payments are more reliable than the tax payments were. Back taxes are often a symptom of a cash-flow problem. If the same squeeze makes you miss loan payments, the unpaid loan becomes a deemed distribution: new taxable income, possibly the 10% additional tax, and a fresh balance owed to the same IRS you were trying to pay off. Fix the cash-flow pattern, or at least set aside the next quarter’s estimate, before you borrow.
When it can still make sense
A plan loan isn’t always a mistake. It can beat high-interest debt, it can beat an IRS balance that keeps growing, and it can beat taking a withdrawal outright, which triggers tax and often a penalty. If you go ahead, look at savings set aside for the purpose, a smaller purchase, or waiting a year first. Get the plan’s loan and repayment terms in writing. Borrow the least you can for the shortest term you can afford, keep contributing while you repay so new money keeps compounding, and know what happens to the loan if your job or your business changes.
The bottom line
The details answer what the marketing pages never quite say: many accounts can’t lend at all, and the arrangement that can interrupts the one thing retirement money does best.
Save for the big purchase separately. Let the retirement account compound.
Keeping that cash separate is its own discipline. It’s the same one behind building a small business emergency fund and keeping ready cash, and the reason profitable businesses still run out of cash.
This article is general education, not investment, tax, or legal advice. Retirement plan rules, limits, and plan documents vary, and your facts matter. Before borrowing from or moving a retirement account, review your plan document and talk with a qualified advisor about your situation.
Are You Ready to Take Control of Your Business Finances?
Most back-office problems don’t live where owners look for them first — not in the tool, not in the person, but in the handoffs and decisions nobody ever made explicit. At ProjectBits Consulting, Tax Ready Bookkeeping starts with a structured diagnostic: we put a number on each part of your books, name what’s actually plateaued, and show you the receipts before recommending any work. You leave with a clear picture you can act on — whether you work with us or not.
The diagnostic precedes the remedy. The Tax Ready Assessment is the front door — a no-obligation walk through where your books actually stand this month. Apply now for your Tax Ready Assessment, or explore the thinking behind it in the book, Tax Ready Bookkeeping.